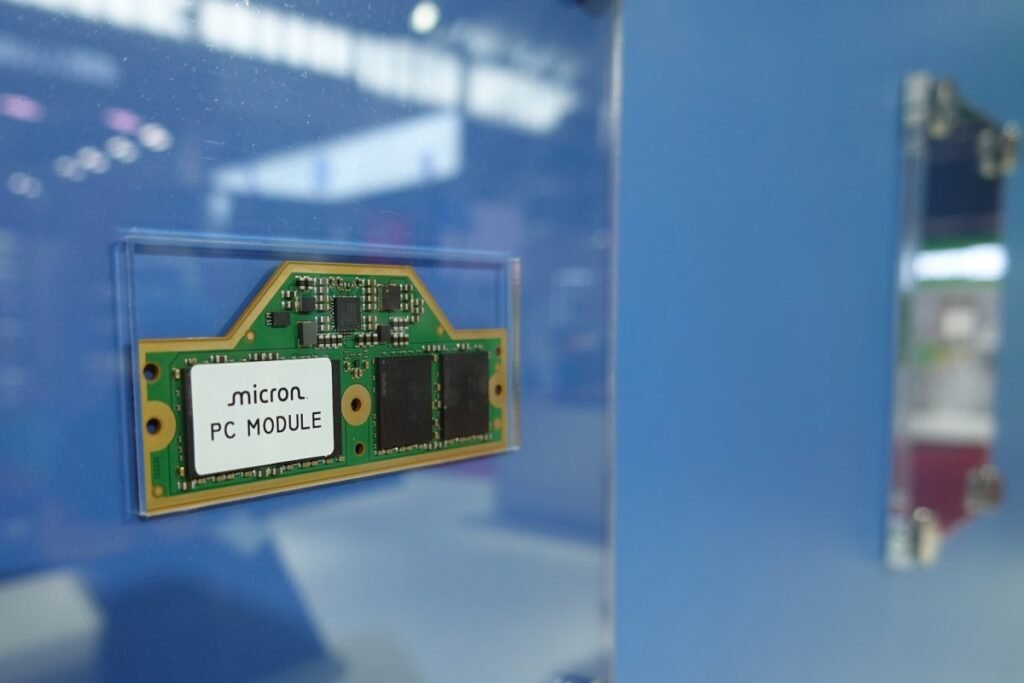
Micron Technology, the Boise-based memory chip manufacturer, has become the latest obsession for Wall Street investors. As the global AI-driven supply crunch for memory chips intensifies, the company’s ability to capitalize on this demand has triggered a historic surge in its valuation, briefly surpassing tech titans Meta and Tesla this past Thursday.
A Meteoric Rise in Market Valuation
Micron’s financial trajectory has been nothing short of extraordinary. The company closed Friday with a market capitalization near $1.27 trillion, trailing Meta at $1.39 trillion and Tesla at $1.42 trillion. This valuation marks a massive shift for a stock that spent years trading below $100 prior to mid-2025. In the last month alone, Micron’s share price skyrocketed over 236%, finishing Friday at $1,132 per share.
Once known primarily for consumer-grade memory cards for PCs and smartphones, the company has successfully pivoted to become a critical backbone of the modern AI infrastructure.
The “RAMageddon” Effect: Why Memory is King
The current market frenzy is fueled by the massive buildout of AI data centers. These facilities require vast amounts of system memory—specifically DRAM, NAND, and High-Bandwidth Memory (HBM)—far exceeding the capacity needed for standard laptops.
Industry giants like Nvidia and hyperscalers including Microsoft, Amazon AWS, Google, Meta, and Oracle are aggressively securing supply. This competition has forced other sectors, from PC manufacturers like Dell and HP to various device makers, to stockpile inventory. This supply-demand imbalance, coined “RAMageddon,” is expected to persist into 2027, simultaneously driving up costs for consumer electronics like Apple products and Xbox consoles.
Blockbuster Earnings and Strategic Shifts
Micron’s recent third-quarter earnings report underscored its dominance. Revenue quadrupled year-over-year to $41.45 billion, while profits surged from $1.88 billion to $28.2 billion. Looking ahead, the company forecasts fourth-quarter revenue between $49 billion and $51 billion.
To mitigate the historical volatility of the memory industry—where expensive capacity expansions often lead to market gluts—Micron is securing its future through long-term supply agreements. The company has finalized 16 strategic customer contracts, including partnerships with Nvidia and the AI lab Anthropic. Management asserts these deals will fundamentally transform its business model.
Analyst Outlook: Durable Growth or Temporary Spike?
Wall Street analysts are increasingly optimistic about Micron’s potential to mirror Nvidia’s success. Sebastien Naji, a tech analyst at William Blair, emphasized that demand continues to outpace the industry’s ability to bring new cleanroom manufacturing space online.
“Given the strong likelihood of continued ASP growth in the coming quarters and improving revenue visibility thanks to a rapidly expanding set of long-term agreements (SCAs) with key customers, we see potential for more durable earnings growth and reiterate our Outperform rating,” Naji stated.
While the long-term sustainability of this cycle remains a subject of debate, Micron’s brief ascent past some of the tech industry’s largest players signals a new era in hardware dominance.

Leave a Reply